Before we discuss what a DuPont Analysis is, let’s start with a question for you. A company reports a Return on Equity (ROE) of 20%, or maybe you calculate it yourself. Is 20% ROE good? On the surface, many would say yes. But could the ROE number be masking certain issues with the company?
The answer to this is yes. It’s possible. And we can uncover these issues using a concept known as DuPont Analysis.
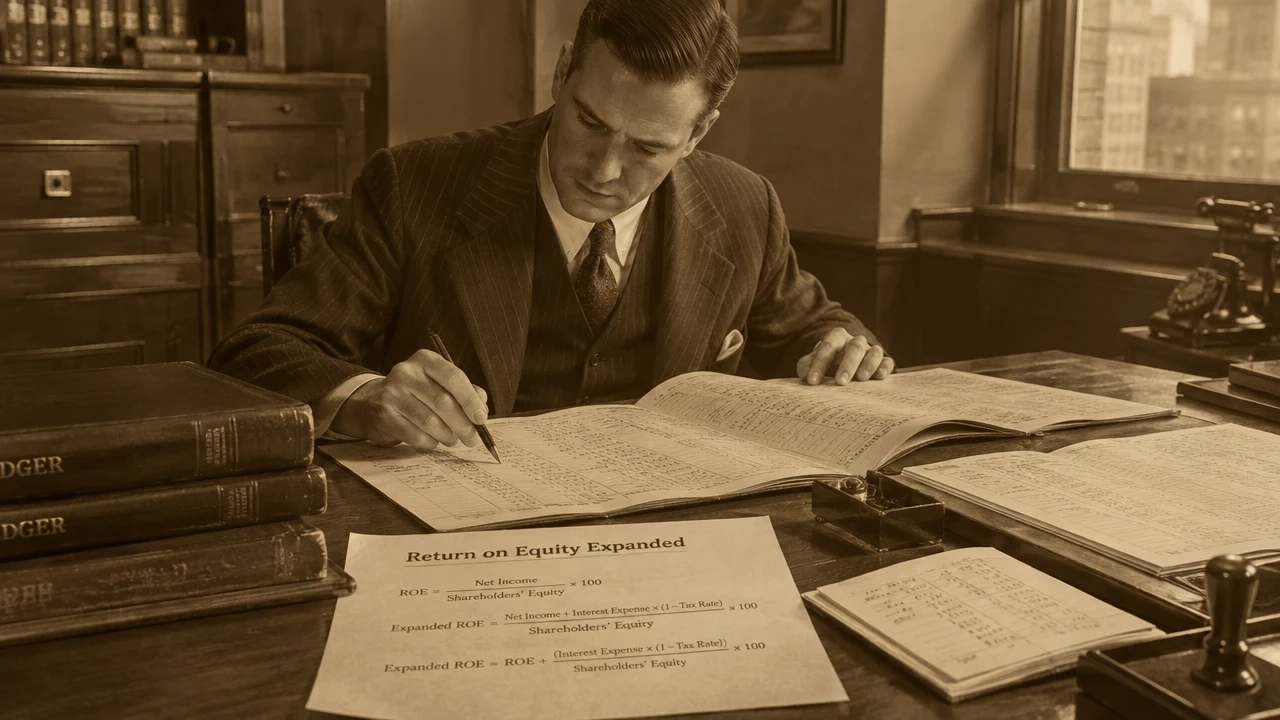
The standard ROE calculation is net income divided by equity. That data is readily available in the income statement and the balance sheet.
Where the Name Came From
DuPont executive Frank Donaldson Brown derived the formula in the 1920s. He noticed that the ROE formula is essentially shorthand for a few components that tell a deeper story when expanded.
So, ROE could be rewritten as follows:

Here is how the standard formula would be expanded (Sales/Sales = 1, Average Assets / Average Assets = 1)
Net Income * 1 * 1 / Equity = Net Income / Equity (which is the standard equation for ROE).
By leaving the equation in its expanded mode, you now have access to measures that were hidden by the
What is Net Income divided by Sales? It is the formula for the profit margin.

Therefore, the first ratio is the profit margin. An increase from the previous period indicates whether the company is increasing profits. (Good sign for the company).
Sales divided by Average Assets is known as the efficiency ratio.

In other words, how strong are sales relative to its assets? Again, an increase in this number means the company is becoming more efficient.
Finally, the Average Assets divided by Equity is known as the leverage ratio.

This one is a bit trickier because we think of Assets (current assets, long-term assets) as the non-liability component of a balance sheet.
To rectify this “anomaly”, we must consider the accounting equation.
Assets = Liabilities + Equity
This equation confuses many: what does it mean for an asset to be the sum of its liabilities and equity? Think of it in terms of how the assets were funded. Once you start seeing it through that lens, it can become an Aha! Moment for you. Unless you don’t really care about accounting. But then again, why would you even be reading this in the first place, if that were the case?
Companies can fund assets (you know, the things that make the company money) by borrowing money or selling stock. If there are no liabilities, then the company is 100% funded through its equity.
The opposite extreme is a bit more delicate, as mathematically, having equity of 0 makes the leverage ratio undefined. Imagine a business with $100 in assets and $99 in liabilities. The only thing keeping shareholders’ equity from hitting zero is that proverbial first dollar the owner framed and hung on the wall. With $1 of equity supporting $100 of assets, the equity multiplier would be a whopping 100×.
The point is that most businesses operate somewhere in the middle, with a mix of equity and debt financing.
NOTE: Site owner may receive a commission for purchases made through the links on this page with no extra cost to you.
What About the Hidden Issues?
Unlike the profit margin ratio and the efficiency ratio, you’d want to see the leverage ratio stay at a manageable level or, even better, have it decrease. Debt is not always a negative drag on a company. Still, if the other two components are not increasing in line with increased debt, you should consider that as a warning or even a red flag, depending on the severity.
Let’s go through an example (with real numbers from Stock Analysis) to show how this concept works and to ensure the expanded version of ROE equals the standard version.
Here are the numbers from the Balance Sheet of DuPont:

And the income statement:

We’ll use the numbers from FY2024 and FY2023, as the company did not do as well in FY2025. We’ll discuss the nuances of the negative numbers later.
These numbers were taken from the Income Statement and Balance Sheet for the DuPont company:

First, notice that the Standard ROE and the Expanded DuPont numbers match (as they should).
If you want to run a DuPont analysis yourself, you can find all the numbers in Stock Analysis (SA). You can do this for any company that SA covers (which is quite a lot). But here are the financial statements for $DD.
Use this link, and for a special SA promotional offer, use FME to receive a 10% discount on your order.
Interpretation
The ROE numbers are super low for $DD. Although this is not investing advice, experienced investors would likely not consider investing in the company due to the extremely low ROE. Investors often look for at least 10%, and even higher.
Although the company is not positioned well, one positive is that ROE has improved since FY2023. The Up, Up, Down pattern is exactly what you’d want to see for the DuPont analysis. In other words, profit margins are up, efficiency is up, and the leverage ratio went down a bit.
Quite often, you may see ROE numbers in the 20% or more range. Before getting too excited, run a DuPont analysis to make sure leverage is driving the number so high. That’s the purpose of the DuPont analysis overall. It shows which components drive a high ROE.
Taking an Average of Balance Sheet Numbers
Investors work with three financial statements published by companies. One key feature of the income statement is that it spans the activity of a specified period (usually quarterly and yearly in the United States; companies can also produce these monthly or at other periodicities).
The balance sheet, by contrast, is a snapshot, a moment in time. So, when you combine the numbers, there is a bit of a mismatch. In some cases, it may not matter much. But the potential exists.
Companies are unlikely to start tracking their balance sheet on an ongoing basis as they do with the income statement. A good compromise is to average the balance sheet numbers from the previous and current periods and divide by 2.
With DuPont Analysis, the Assets and Equity items are the ones that you perform the average calculations on. For instance, our example was for FY2024 and FY2023. You take the results from these years, add them together, and divide by 2. This average better aligns with the periodicity of the income statement numbers. It’s not perfect, but certainly an improvement. The same averaging applies to the equity line item.
Stock Analysis Has Everything You Need for DuPont Analysis
Stock Analysis includes the numbers you need, including at least ten years of history (usually more). Even better, subscribing is incredibly affordable. Start running your DuPont Analysis now. Use Coupon Code FME for 10% off.

Be First to Comment